Bloomberg Professional Services
- Thematic equity leadership broadened in 2026, with genomics, neuro mental health, cloud and cybersecurity gaining momentum alongside AI and semiconductors.
- Cloud and cybersecurity returned about 29% and 28% over the past three months, while semiconductors and compute infrastructure declined 18% and 9%, respectively.
- The rotation does not appear to indicate an AI slowdown as earnings remain robust: semiconductor median sales growth rose to 29.4% and compute infrastructure’s to 15.5%, even as both themes declined over the past three months.
This article includes analysis from BI strategist Jessica Lin, Thematic Strategist at Bloomberg Intelligence
AI and semiconductor stocks have dominated thematic equity performance, but market leadership has begun to extend into areas including cloud, cybersecurity, genomics and neuro mental health. The shift raises an important question for thematic investors: is leadership broadening, or is momentum simply moving away from AI?
PRODUCT MENTIONS
A thematic rotation portfolio tracked by Bloomberg Intelligence gained 27% over the past year (YTD as of Oct 16, 2026). The portfolio ranks BI themes on a blend of trailing six- and 12-month returns, equal-weights the top five and rebalances monthly. Note, the exposure of BI themes is replicated by Total Return variants of Aggregate Equal Weighted versions of Bloomberg Thematic Equity Indices in USD.
This article looks at how thematic leadership has changed in 2026, which areas are gaining momentum and what fundamentals and market breadth indicate about the rotation beyond AI.
How broadly is thematic leadership expanding?
Considering the composition of the portfolio over the last one year, the returns did not come from a stable set of holdings. The top five themes in the portfolio have rotated repeatedly in 2026 through Sep. 2026, so the gain likely reflects a succession of leaders rather than sustained strength in any single theme.

The composition of the portfolio illustrates that rotation. Bloomberg Transition Metals Index (BTMAET Index) had an early lead from January 2026 through March 2026, with Bloomberg Nuclear Index (BNUAET Index) and Bloomberg Space Index (BSPCAET Index) alongside it. Bloomberg Semiconductors Index (BSEAET Index) took first place in April 2026 and has held it every month since. Beneath them, the remaining four positions changed frequently since then.
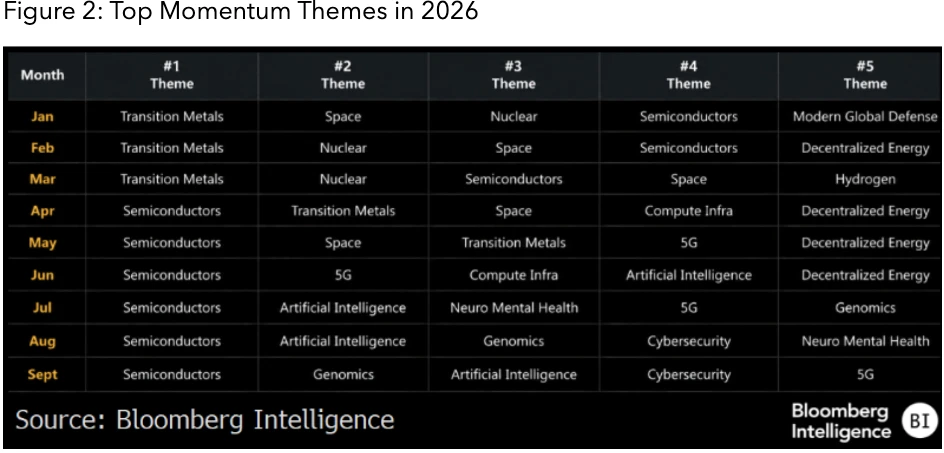
Leadership then shifted toward healthcare, with Bloomberg Genomics Index (BGEAET Index) and Bloomberg Neuro Mental Health Index (BNMAET Index) joining the top five in the second half. If we look at sub-components driving this movement, Genomics’ gains are led by therapeutics, with devices and services also contributing. Neuro mental health is led by cannabinoid and psilocybin exposure, followed by non-opioid therapeutics and neuro.
In August 2026, Bloomberg Cybersecurity Index (BCYAET Index) joined the top five, in line with the narrative of increased focus on tighter AI safeguards taking hold, which could drive further security spending, as stronger guardrails may require additional AI and compute investment.

Tech leadership broadens toward cloud and cyber
Within technology, leadership is shifting toward cloud (BCLAET Index) and cybersecurity (BCYAET Index) after semiconductors (BSEAET Index) and compute infrastructure (BCIAET Index) drove earlier gains. Cloud and cybersecurity have returned about 29% and 28% over the past three months, leading BI’s accelerating-tech themes, compared with declines of 18% and 9% over the corresponding period for semiconductors and compute infrastructure. The earlier AI-led gains nonetheless remain intact: semiconductors and AI are still up 63% and 41% this year, though semiconductor breadth,measured as percentage of constituents of an index above their 200-day moving averages, has narrowed sharply.
If we analyze breadth of each tech theme, it is led mainly by recent software gains, with 84% of cybersecurity and 70% of cloud constituents above their 200-day moving averages.

Does the software rotation signal an AI slowdown?
Fundamentals provide additional context for the rotation. Cybersecurity’s median sales growth rose to 16.6% from 14.7% three months ago as breadth of the theme jumped 32 percentage points, while cloud’s 16.1% growth was roughly steady as its breadth more than doubled. Both themes also saw P/S multiples expand, suggesting that valuations contributed to recent gains alongside fundamentals. Semiconductors nonetheless retain the strongest growth at 29.4%, up nearly 7 percentage points, despite a 17% three-month decline and P/S contraction to 5.1x from 6.3x.
Compute infrastructure shows a similar pattern, with median sales growth rising to 15.5% from 13.1% even as the theme fell 9% and its P/S contracted. AI’s sales growth also improved, to 24.6%, as its multiple contracted. The divergence between falling prices and rising growth suggest that technology leadership has broadened without a corresponding slowdown in AI-related fundamentals.

Longer-term returns came without materially deeper drawdowns
The pattern is not confined to 2026. Since 2019, the top five momentum theme portfolio has gained more than 625% cumulatively, equivalent to a 29% annualized return, compared against 18% for the Bloomberg 500 Index, 14% for the Bloomberg World Index and 18% for an equal-weight portfolio of all BI thematic indices.
That return advantage also came without materially deeper drawdowns. The portfolio’s maximum drawdown was 32%, roughly in line with the Bloomberg 500 Index and the Bloomberg World Index, and slightly below the 33% recorded across all themes. The portfolio had a Sharpe ratio of 1.2, indicating stronger historical risk-adjusted performance over the period.

What does broader thematic leadership indicate?
Thematic leadership turned over almost completely in 2026, with only semiconductors and AI carried through from the midyear composition into August. However, turnover has not come at AI’s expense. Semiconductor and compute-infrastructure sales growth both improved even as the performance of the two themes fell over three months and their multiples contracted. Cloud and cybersecurity, meanwhile, led on both returns and breadth.
The broader implication is that thematic leadership is becoming more dynamic, with the portfolio rotating repeatedly through 2026. Breadth and sales-growth data suggest that fundamentals have accompanied the recent rotation, even as valuation expansion contributed to gains in cloud and cybersecurity.
To learn more about Bloomberg Thematic Indices Methodology click here. Bloomberg Terminal subscribers can access this analysis along with associated data via BI <GO>.
Index Name | BI Theme Universe(s) | Total Return Ticker
Bloomberg 5G Aggregate Equal Weight Index | 5G | B5GAET
Bloomberg Artificial Intelligence Aggregate Equal Weight Index | Artificial Intelligence | BAIAET
Bloomberg Autonomous Vehicles Aggregate Equal Weight Index | Autonomous Vehicles | BAVAET
Bloomberg Biodiversity Aggregate Equal Weight Index | Biodiversity | BBDAET
Bloomberg Biofuels Aggregate Equal Weight Index | Biofuels | BBFAET
Bloomberg CCUS Aggregate Equal Weight Index | CCUS | BCCAET
Bloomberg Circular Materials Aggregate Equal Weight Index | Circular Materials | BCMAET
Bloomberg Cloud Aggregate Equal Weight Index | Cloud | BCLAET
Bloomberg Compute Infra Aggregate Equal Weight Index | Compute Infra | BCIAET
Bloomberg Cybersecurity Aggregate Equal Weight Index | Cybersecurity | BCYAET
Bloomberg Decentralized Energy Aggregate Equal Weight Index | Decentralized Energy | BDEAET
Bloomberg Digital Payments Aggregate Equal Weight Index | Digital Payment | BDPAET
Bloomberg Enterprise Fintech Aggregate Equal Weight Index | Enterprise Fintech | BEFAET
Bloomberg Frontier Tech Aggregate Equal Weight Index | Frontier Tech | BFTAET
Bloomberg Future of Finance Aggregate Equal Weight Index | Future of Finance | BFFAET
Bloomberg Genomics Aggregate Equal Weight Index | Genomics | BGEAET
Bloomberg Grid Tech Aggregate Equal Weight Index | Grid Tech | BGTAET
Bloomberg Hydrogen Aggregate Equal Weight Index | Hydrogen | BHYAET
Bloomberg Metaverse Aggregate Equal Weight Index | Metaverse | BMVAET
Bloomberg Modern Global Defense Aggregate Equal Weight Index | Modern Global Defense | BMDAET
Bloomberg Neuro Mental Health Aggregate Equal Weight Index | Neuro Mental Health | BNMAET
Bloomberg Nuclear Aggregate Equal Weight Index | Nuclear | BNUAET
Bloomberg Obesity Aggregate Equal Weight Index | Obesity | BOBAET
Bloomberg Plant Based Food Aggregate Equal Weight Index | Plant Based Food | BPBAET
Bloomberg Prepare & Repair Aggregate Equal Weight Index | Prepare & Repair | BPRAET
Bloomberg Robotics Aggregate Equal Weight Index | Robotics | BROAET
Bloomberg Semiconductors Aggregate Equal Weight Index | Semiconductors | BSEAET
Bloomberg Solar Aggregate Equal Weight Index | Solar | BSOAET
Bloomberg Space Aggregate Equal Weight Index | Space | BSPCAET
Bloomberg Sports Aggregate Equal Weight Index | Sports | BSPAET
Bloomberg Transition Metals Aggregate Equal Weight Index | Transition Metals | BTMAET
Bloomberg Water Aggregate Equal Weight Index | Water | BWAAET
Bloomberg Wind Aggregate Equal Weight Index | Wind | BWIAET
The data and other information included in this publication is for illustrative purposes only, available “as is”, non-binding and constitutes the provision of factual information, rather than financial product advice. BLOOMBERG and BLOOMBERG INDICES (the “Indices”) are trademarks or service marks of Bloomberg Finance L.P. (“BFLP”). BFLP and its affiliates, including BISL, the administrator of the Indices, or their licensors own all proprietary rights in the Indices. Bloomberg L.P. (“BLP”) or one of its subsidiaries provides BFLP, BISL and its subsidiaries with global marketing and operational support and service. Certain features, functions, products and services are available only to sophisticated investors and only where permitted. Bloomberg (as defined below) does not approve or endorse these materials or guarantee the accuracy or completeness of any information herein, nor does Bloomberg make any warranty, express or implied, as to the results to be obtained therefrom, and, to the maximum extent allowed by law, Bloomberg shall not have any liability or responsibility for injury or damages arising in connection therewith. Nothing in the Services or Indices shall constitute or be construed as an offering of financial instruments by Bloomberg, or as investment advice or investment recommendations (i.e., recommendations as to whether or not to “buy”, “sell”, “hold”, or to enter or not to enter into any other transaction involving any specific interest or interests) by Bloomberg. Information available via the Index should not be considered as information sufficient upon which to base an investment decision. All information provided by the Index or in this publication is impersonal and not tailored to the needs of any person, entity or group of persons. Absence of any trademark or service mark from this list does not waive Bloomberg’s intellectual property rights in that name, mark or logo. For the purposes of this publication, Bloomberg includes BLP, BFLP, BISL and/or their affiliates.
BISL is registered in England and Wales under registered number 08934023 and has its registered office at 3 Queen Victoria Street, London, England, EC4N 4TQ. BISL is authorised and regulated by the Financial Conduct Authority as a benchmark administrator.
© 2026 Bloomberg. All rights reserved.